
It starts with life insurance.
- If the insured person dies while coverage is in force, the policy pays a death benefit to named beneficiaries, subject to its terms.
A CLEARER FINANCIAL ROAD AHEAD
We’ll guide you through how it works, what it costs, and whether it may belong in your plan. Start with the short guide, or keep scrolling for the videos, illustrations, examples, and tradeoffs.
Answer five quick questions for an educational starting point built around your priorities. No email required.
01 / START WITH THE BASICS
In plain English: an IUL is permanent life insurance with a cash-value feature.
Growth and coverage depend on the contract, funding, costs, and time. An illustration is an estimate, not a promise.
Someone who needs lasting life coverage, can comfortably fund it over time, and is willing to review costs and performance may want to compare IUL with other ways to meet those needs.
It may be a poor fit if you need low-cost, temporary coverage; may need the money soon; cannot keep up funding; expect market-like returns with no risk; or want a simple account you do not have to monitor.
IUL is more complicated to explain than term insurance or a basic savings account: it combines insurance costs, index-crediting rules, and long-term funding. That can make it less familiar, but it does not establish why a particular advisor has—or has not—recommended it.
Agents may represent different insurers and products, and compensation can be part of the sales relationship. Ask: “Which alternatives did you compare? Which companies can you offer? How are you paid on each option?”
In Texas, replacing a policy just to earn a new commission is illegal. Review any proposed replacement carefully and ask for the reasons in writing.
These are possible features, not guaranteed outcomes—and each has conditions.
Interest may be credited using a market index formula, within the policy's caps, participation rates, and other terms.
Understand the guardrailsCash value generally grows tax-deferred. Certain access may receive favorable tax treatment if policy and tax rules are followed.
Compare tax treatmentThe policy can pay beneficiaries while coverage remains in force. Some contracts offer living-benefit riders with limits and conditions.
See how it worksTHE BIG PICTURE
Watch Judy’s original IUL explainer, then explore the details at your own pace.
Examples are educational. Available features and actual results depend on the policy, underwriting, and contract terms.
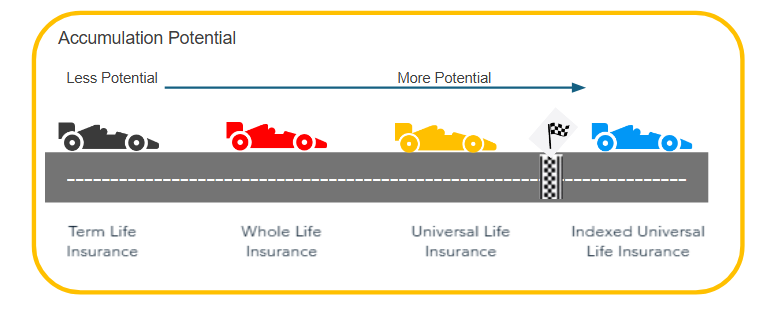
Different vehicles. Different purposes. Term life generally provides coverage for a set period without cash accumulation. Whole life generally includes guarantees and fixed premiums. Universal life offers flexibility. Indexed universal life adds index-linked crediting choices.
The right fit depends on your protection needs, budget, time horizon, and willingness to manage a policy. No type automatically wins for everyone.
02 / YOUR NUMBERS, YOUR ASSUMPTIONS
Change the inputs, compare scenarios, and see the math behind every year. An educational model—not a policy quote or actual IUL benefit illustration.
Your numbers stay in your browser. Open calculator separately ↗
FUEL YOUR JOURNEY
Understanding when you pay taxes helps you choose the right mix of financial tools.
Earnings may be taxed as you go, reducing what stays available to grow.
Defer taxes on growth until a taxable withdrawal. Your future tax rate matters.
Some tools offer favorable tax treatment when the relevant requirements are met.
JUDY’S ORIGINAL COMPARISON
Watch the three cars move through a simplified tax comparison. The source illustration uses different assumptions for each account, so it is a teaching visual—not an apples-to-apples forecast, policy quote, or expected result.
Account rules differ. IUL policy values are not guaranteed, and costs can reduce cash value.
A SIMPLE WAY TO THINK ABOUT IT
Think of a marked lane. In this example, the lane limits only the interest credit:
In an annual point-to-point strategy, the index's change is measured over a defined year. At the next reset, a new measuring period begins. Credited interest follows the contract's rules; it does not eliminate policy costs or guarantee future growth.
Caps, participation rates, spreads, index choice, timing and contract terms can change the result. Insurers may adjust non-guaranteed terms. The S&P 500 is an index example; an IUL is not a direct investment in it.
Try a change below. The interest credit in this example stays between $0 and $10 per $100. This only shows interest credited before policy charges.
At +8%, the example credit is $8 per $100 in the strategy, before policy charges.
Example terms only: 0% floor, 10% cap, full participation, no spread. Not a current product offer or policy projection. Actual terms vary by policy.
THE ROAD, ONE STEP AT A TIME
Choose coverage and crediting options based on your needs. Medical and financial underwriting determine what is available.
Part covers insurance and policy charges. The balance supports the policy's cash value, subject to contract terms.
Interest is credited under the strategy you select. Growth is tax-deferred, while ongoing charges continue.
Monitor performance and funding. Loans or withdrawals may provide access, with costs, tax rules, and effects on coverage.
LIFE DOESN'T FOLLOW A STRAIGHT LINE
Available cash value may support more than retirement. Participating policy loans can offer access while eligible value remains linked to a crediting strategy.
A policy loan is a loan against your policy, not a withdrawal of free earnings. Participating loan provisions may keep some value eligible for index-linked crediting. Loan interest is still charged, and there is no guarantee that crediting will exceed the loan rate.
Repayment can be flexible, but unpaid interest may compound. Loans and withdrawals reduce available cash value and death benefits and may cause a lapse. Additional premiums may be needed. See the full policy and a current carrier illustration.
Access is not automatically tax-free. Withdrawals above basis, surrender, lapse with a loan, and modified endowment contract (MEC) rules can create taxable income. MEC distributions may also trigger an additional tax before age 59½. Consult your tax professional.
Before you watch Judy’s original explainer: a few graphics simplify tax treatment, loan eligibility, borrowing costs, and interest crediting. These features vary by contract and are not guaranteed. Use the explanation as a starting point; rely on current policy terms and a carrier illustration before making decisions.
A MORE ADVANCED CONVERSATION
Some strategies, including programs marketed as Kai-Zen, combine your contributions with borrowed funds to support a larger policy. More funding may create more potential benefits—and additional financing risk.
Explore whether it fitsFinancing is not free growth. Interest rates, credit availability, policy performance, fees, and a realistic loan exit plan all matter. Qualification and terms must be confirmed with the program provider.
A meaningful estimate needs the carrier's complete illustration, the financing agreement, applicable fees, funding schedule and loan-exit assumptions. The planning calculator above does not model financing or promise a multiple of your contribution. Projected loan exit is not guaranteed; trust and administrative fees may be non-refundable under the program's terms.
GOOD QUESTIONS. CLEAR STARTING POINTS.
Every situation is different. The next step is a conversation about yours.
Ask an advisor a questionIt may be worth comparing when someone needs long-term life coverage, can comfortably fund it, and accepts the costs and ongoing review. It may be a poor fit when coverage is only needed temporarily, money may be needed soon, or the person expects a simple, guaranteed investment. Compare it with term coverage plus separate savings or investments.
No. It is a working educational model using the assumptions you enter. It does not estimate actual death benefits, insurance charges, policy cash value, underwriting outcomes or tax-free income. To evaluate a policy, request its carrier illustration, including guaranteed and non-guaranteed values.
Yes. The floor applies to index crediting, not your overall policy balance. Insurance charges, expenses, loans and withdrawals can reduce value. If the policy is underfunded, additional premiums may be required to prevent lapse.
Access depends on available cash value and the contract. Surrender charges, loan interest and tax consequences can apply. Early years may have little accessible value. Loans and withdrawals can reduce coverage and jeopardize the policy if not managed.
You’ll have 30 minutes with an advisor to discuss your goals, understand the options, and decide on a useful next step. Josh Harcus is currently available for these introductory calls. Bring your questions and, if you used the calculator, your downloaded scenario. No enrollment is required to book.
03 / YOUR NEXT MOVE
Use a free, 30-minute introductory call to discuss your priorities, understand the options, and decide whether there is a useful next step. Josh Harcus is one of Closing Culture’s advisors and is available for introductory conversations.
Find a time with an advisorGoogle Meet · Weekdays, 10 a.m.–4 p.m. Central, subject to availability
Advisor · Closing Culture